Does an offer in compromise apply to a non-tax federal debt collected through TOP?

Legal Eagle
Legal Eagle

135,460 satisfied customers

View context
Solved

Thank you for chatting with me on this. The short answer is that an offer in compromise is generally an IRS tool for tax debt, and it does not directly apply to an SEC civil penalty that has been referred to the BFS through TOP. The federal government does have a separate compromise process for non-tax debts, and your situation may qualify. The debt also does not automatically pass to your wife when you die.

That's the short answer. Here is the long answer:

The legal framework here is the Federal Claims Collection Act, codified at (31 U.S.C. § 3711), and the related regulations at (31 C.F.R. Part 902), which give federal agencies authority to compromise, suspend, or terminate collection of non-tax debts. The BFS and the SEC both have authority to accept a compromise offer on a debt like yours.

The 15% deduction from Social Security is itself governed by a separate statute, (31 U.S.C. § 3716(c)), and its implementing regulation at (31 C.F.R. § 285.4), which caps offsets against Social Security benefits at the lesser of 15% or the amount over a protected floor. This is the authority that allows the government to take a slice of your monthly benefit at all, separate from the compromise process itself.

Because your balance has grown to $890,000 despite years of TOP offsets, and given your age and financial circumstances, you have a legitimate basis to request a formal compromise. Debts owed solely by you do not transfer to a surviving spouse upon your death unless she independently co-signed or is otherwise legally liable for the underlying obligation. Personal civil penalty debts are not inherited by a spouse.

Here is what you can do legally, step-by-step:

Contact the BFS directly and request a compromise or hardship review under (31 C.F.R. Part 902). Ask them to send you the form for submitting a compromise offer on a non-tax federal debt. You can reach BFS at 1-888-826-3127 or at https://www.fiscal.treasury.gov/dms.

Write a short financial hardship statement documenting your age, your fixed income, your current assets and liabilities, and the fact that 15% of your Social Security has already been offset for four years. This is the backbone of any compromise request and shows that full collection is not realistic.

Send a written inquiry to the SEC asking whether it retained any collection authority or whether everything was fully transferred to BFS. Some settlement debts remain partially under SEC jurisdiction even after TOP referral. You can reach the SEC at https://www.sec.gov/tcr.

Once you know who holds primary collection authority, submit a formal written compromise offer citing your age, the years of offset already applied, and the practical impossibility of full collection within your lifetime. Frame it around the standard in 31 C.F.R. Section 902.2, which allows compromise when the government is unlikely to collect the full amount.

Bonus tip: The government is generally more receptive to compromise when a debtor can show that continued collection produces diminishing returns. Because you are 75 and on a fixed income with no near-term ability to pay the remaining $890,000, your profile fits the type of case that federal agencies are authorized to close or settle. Putting that in writing, clearly and without embellishment, gives the agency what it needs to act.

Does that help clarify things? I want to make sure I didn't leave anything out.

0

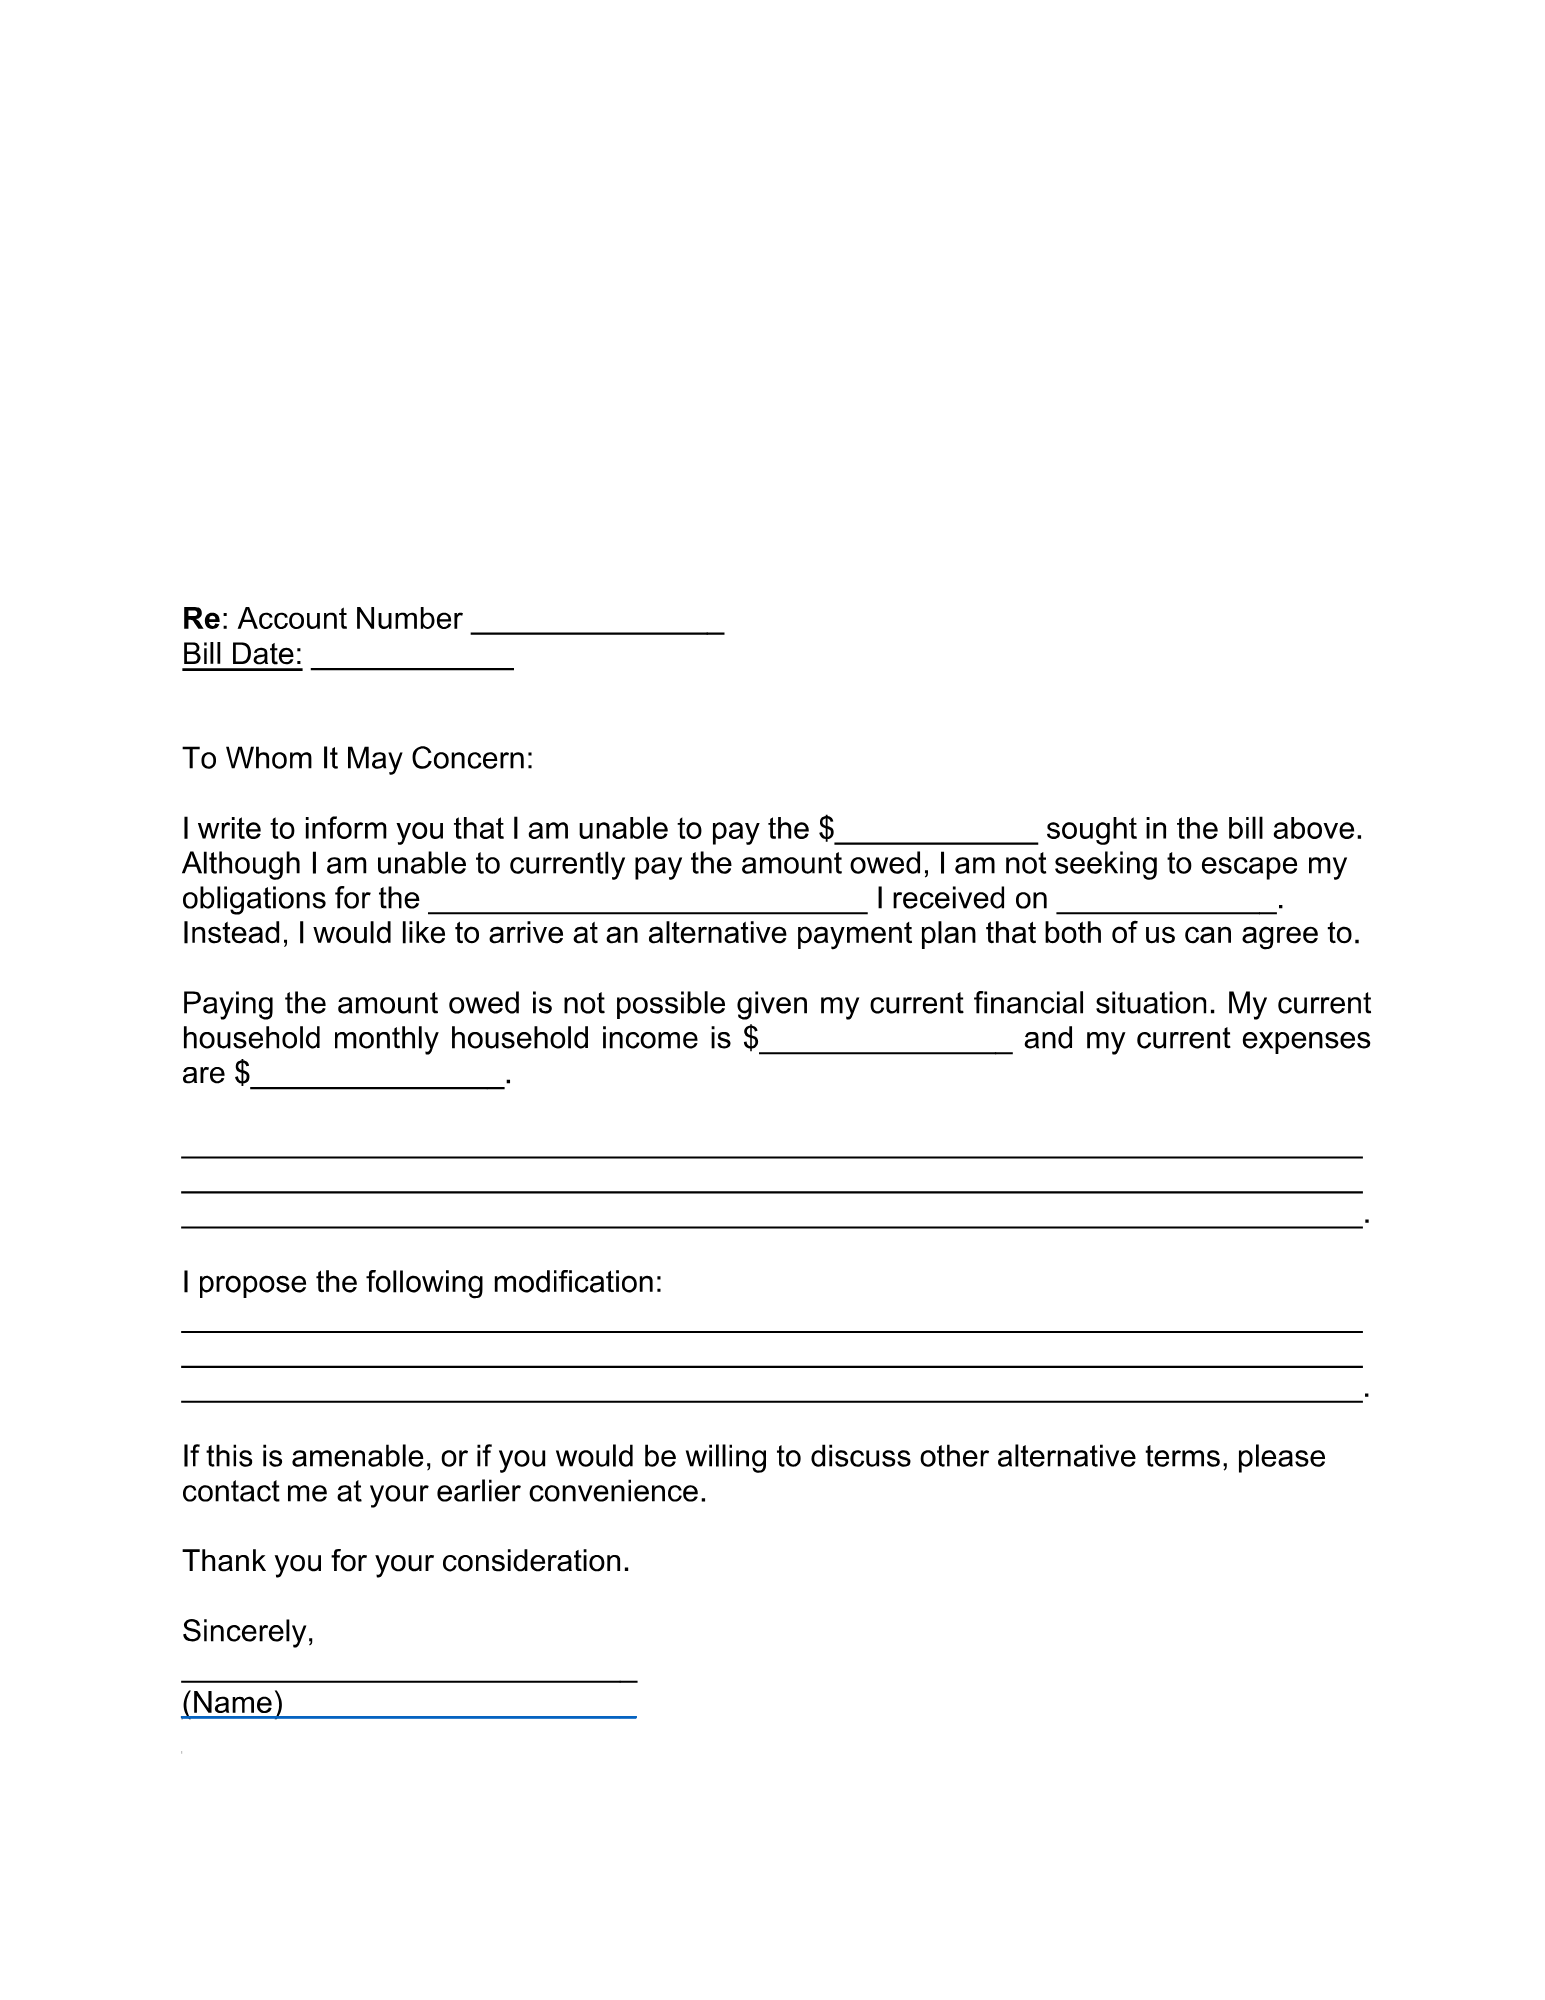
Financial Hardship Letter

Full Conversation


Can I use an offer in compromise to resolve a non tax federal debt?

Lexi

Lexi, Chatbot

I understand that dealing with federal debt can be stressful. Have you already submitted an offer in compromise for your non-tax federal debt?

No.

Lexi

Lexi, Chatbot

What type of non-tax federal debt are you trying to resolve?

A remaining balance due from an SEC settlement that was transferred via TOP to the Bureau of Fiscal Services.

Lexi

Lexi, Chatbot

Is there anything else the Lawyer should know before I connect you? Rest assured they'll be able to help with your SEC settlement debt.

The case was settled in 2018 with $1,366,000 due within a year. I paid the first two installments of $342,000 each in a timely manner, then advised the SEC I would have trouble paying the balance. I didn't hear from them for several years, so I thought I was in the clear. Then I got a TOP letter four years ago, and 15% of my Social Security has been deducted each month since, with no further communication until last week when I received a letter from the BFS saying I now owed $890,000. I'm 75 years old.

Legal Eagle

Legal Eagle

Hello, I'm Legal Eagle. I'm an attorney who works in your area of law, and I'll help you sort this out today. I've read what you shared, so let's go over what's happening and what your best next steps look like. You mentioned receiving a letter from the BFS about an SEC settlement debt. Is that correct?

Yes.

Legal Eagle

Legal Eagle

Have you received any formal notices or communications from the SEC or the Bureau of Fiscal Services regarding the possibility of an offer in compromise for your debt?

No.

Legal Eagle

Legal Eagle

Have you tried reaching out to the Bureau of Fiscal Services or the SEC to discuss your current financial situation and explore any possible options for resolving the debt?

Not yet. I want to see what my options are and if I should use an attorney to help me with this. I also don't know if, if I die, this debt transfers to my wife, or if I take it to my grave.

Legal Eagle

Legal Eagle

Ok! Did you need to tell me anything else? If not, I can start with answering your question.

Nothing else to tell.

Legal Eagle

Legal Eagle

Ok! I've been working on an answer while we've been chatting, so it'll just be a moment.

Legal Eagle

Legal Eagle

Thank you for chatting with me on this. The short answer is that an offer in compromise is generally an IRS tool for tax debt, and it does not directly apply to an SEC civil penalty that has been referred to the BFS through TOP. The federal government does have a separate compromise process for non-tax debts, and your situation may qualify. The debt also does not automatically pass to your wife when you die.

That's the short answer. Here is the long answer:

The legal framework here is the Federal Claims Collection Act, codified at (31 U.S.C. § 3711), and the related regulations at (31 C.F.R. Part 902), which give federal agencies authority to compromise, suspend, or terminate collection of non-tax debts. The BFS and the SEC both have authority to accept a compromise offer on a debt like yours.

The 15% deduction from Social Security is itself governed by a separate statute, (31 U.S.C. § 3716(c)), and its implementing regulation at (31 C.F.R. § 285.4), which caps offsets against Social Security benefits at the lesser of 15% or the amount over a protected floor. This is the authority that allows the government to take a slice of your monthly benefit at all, separate from the compromise process itself.

Because your balance has grown to $890,000 despite years of TOP offsets, and given your age and financial circumstances, you have a legitimate basis to request a formal compromise. Debts owed solely by you do not transfer to a surviving spouse upon your death unless she independently co-signed or is otherwise legally liable for the underlying obligation. Personal civil penalty debts are not inherited by a spouse.

Here is what you can do legally, step-by-step:

Contact the BFS directly and request a compromise or hardship review under (31 C.F.R. Part 902). Ask them to send you the form for submitting a compromise offer on a non-tax federal debt. You can reach BFS at 1-888-826-3127 or at https://www.fiscal.treasury.gov/dms.

Write a short financial hardship statement documenting your age, your fixed income, your current assets and liabilities, and the fact that 15% of your Social Security has already been offset for four years. This is the backbone of any compromise request and shows that full collection is not realistic.

Send a written inquiry to the SEC asking whether it retained any collection authority or whether everything was fully transferred to BFS. Some settlement debts remain partially under SEC jurisdiction even after TOP referral. You can reach the SEC at https://www.sec.gov/tcr.

Once you know who holds primary collection authority, submit a formal written compromise offer citing your age, the years of offset already applied, and the practical impossibility of full collection within your lifetime. Frame it around the standard in 31 C.F.R. Section 902.2, which allows compromise when the government is unlikely to collect the full amount.

Bonus tip: The government is generally more receptive to compromise when a debtor can show that continued collection produces diminishing returns. Because you are 75 and on a fixed income with no near-term ability to pay the remaining $890,000, your profile fits the type of case that federal agencies are authorized to close or settle. Putting that in writing, clearly and without embellishment, gives the agency what it needs to act.

Does that help clarify things? I want to make sure I didn't leave anything out.

Boy, does it ever! Thank you so much!

Legal Eagle

Legal Eagle

For sure! Did I thoroughly address your question? If the answer is no, please let me know so I can help! I know it's a lot.

Do I disclose my wife's assets or just mine? Unless it is our home, which has both our names on it. The only other account in my name only is my IRA.

Legal Eagle

Legal Eagle

Your wife's assets are generally not included in a compromise submission unless they are jointly held. The home, since it is titled in both names, counts as a joint asset and should be disclosed. Your IRA is in your name only and gets listed as your asset.

Thank you very much for your help and guidance. I really appreciate it.

Legal Eagle

Legal Eagle

For sure! I want to ensure you feel completely satisfied with our conversation. Were there any details I missed? Did you have any concerns about this issue that still need to be addressed? I'm happy to help.

Not at this time, but I will reach out again if I do.

Legal Eagle

Legal Eagle

I hope I was able to help resolve your issue! If you have any other questions, feel free to ask.

Legal Eagle

Legal Eagle

135,460 satisfied customers

Criminal law, employment law, family law, landlord-tenant, and real estate law.

Legal Eagle
Welcome! Have a similar question?

12 lawyers online now

0:00

By messaging AskALawyer, you agree to our Terms and Privacy Policy.

Disclaimer


By messaging AskaLawyer.com, you agree to our Terms and have read our Privacy Policy.

The information provided on AskaLawyer.com is for general informational purposes only and does not constitute legal advice. While we strive to ensure the accuracy and timeliness of the information presented, we make no guarantees regarding its completeness or applicability to your specific circumstances.

Use of this website does not create an attorney-client relationship between you and AskaLawyer.com or any of its attorneys. Communications through this website, including any responses from attorneys, are not privileged or confidential. For advice tailored to your individual situation, we recommend consulting a licensed attorney in your jurisdiction.

AskaLawyer.com disclaims any liability for actions taken or not taken based on the content of this site. We are not responsible for any third-party content that may be accessed through this website. Reliance on any information provided herein is solely at your own risk.

Ask a Lawyer Logo
Ask a Lawyer Logo
Intake Questions
Step  of 3
Loading...

What's your legal question?

Lexi, Chatbot

How would you like your legal question to be answered?

Online

Loading...

How do you like to pay?

By proceeding with payment, you agree to our Terms and Privacy Policy. You authorize us to charge $ today and $ thereafter until canceled. You may cancel anytime in the My Account section to stop future charges.

Total Due:

After purchasing, your chat will begin with an attorney.

By proceeding with payment, you agree to our Terms and Privacy Policy. You authorize us to charge $ today and $ thereafter until canceled. You may cancel anytime in the My Account section to stop future charges.

Total Due:

After purchasing, your chat will begin with an attorney.

After connecting, your chat will begin with an attorney. After choosing, your chat will continue with Legal AI.

It looks like you already have an account with Ask a Lawyer.

We have sent you a magic link to . Click the link in your email to sign in and continue your chat.

spin

Step of 6 •

You'll receive an email at as soon as the lawyer joins the conversation 🙏🏻😊

Over 90% of lawyers connect within 5 minutes. If you're not online at that moment, don't worry — the lawyer will reply to your message while you're away.

You're also welcome to stay in the chat while waiting to be connected 💬✨

Waiting for lawyer

We couldn't send your message. Please try again.

Your lawyer will reply as soon as possible

If there’s a delay, please don’t worry. Your chat will stay open, and they’ll get back to you as soon as they can. There’s no rush on your end either. You’ll receive an email notification as soon as there’s a new message.

You've reached your AI chat limit

Upgrade your plan to continue chatting and get instant domain-specific answers.

0:00