[MD] How do you clear a federal tax lien for a short sale?

Jon
Jon

556 satisfied customers

View context
Solved

This is a very common type of real estate deadlock where everyone is pushing against different timelines at once. The lender wants a fast answer, the IRS moves slowly, and the buyer is getting frustrated with repeated extensions. The biggest issue is that the lender's suggestion to remove the IRS lien from the ALTA statement is not a real solution and could create even bigger problems.

Even if the lien is removed from the settlement paperwork, the IRS lien still exists in the public records. A federal tax lien attaches to all of the taxpayer's property under (26 U.S.C. § 6321), and a filed notice of lien is effective against later purchasers and lenders under (26 U.S.C. § 6323). A title company in Maryland is not going to issue clean title insurance with a $90,000 federal tax lien attached to the property, and the buyer's lender is unlikely to fund the loan with that lien still in place. The IRS also does not simply transfer a lien onto someone's Social Security number. To clear title legally, the IRS must issue a formal Certificate of Discharge for the property.

The main path forward is usually IRS Form 14135, filed under Internal Revenue Code (26 U.S.C. § 6325(b)(2)(B). Your attorney would argue that after paying the senior mortgage and satisfying the VA minimum net requirement, there is effectively no remaining value in the property for the IRS to collect against. If the IRS agrees its interest in the property has no value, it can approve a discharge of the lien so the sale can close.

The problem is timing. The IRS often says these requests can take at least 45 days to process, which does not fit well with the lender's May 27, 2026 deadline unless an attorney can get the case escalated directly through the local IRS Advisory Office.

0

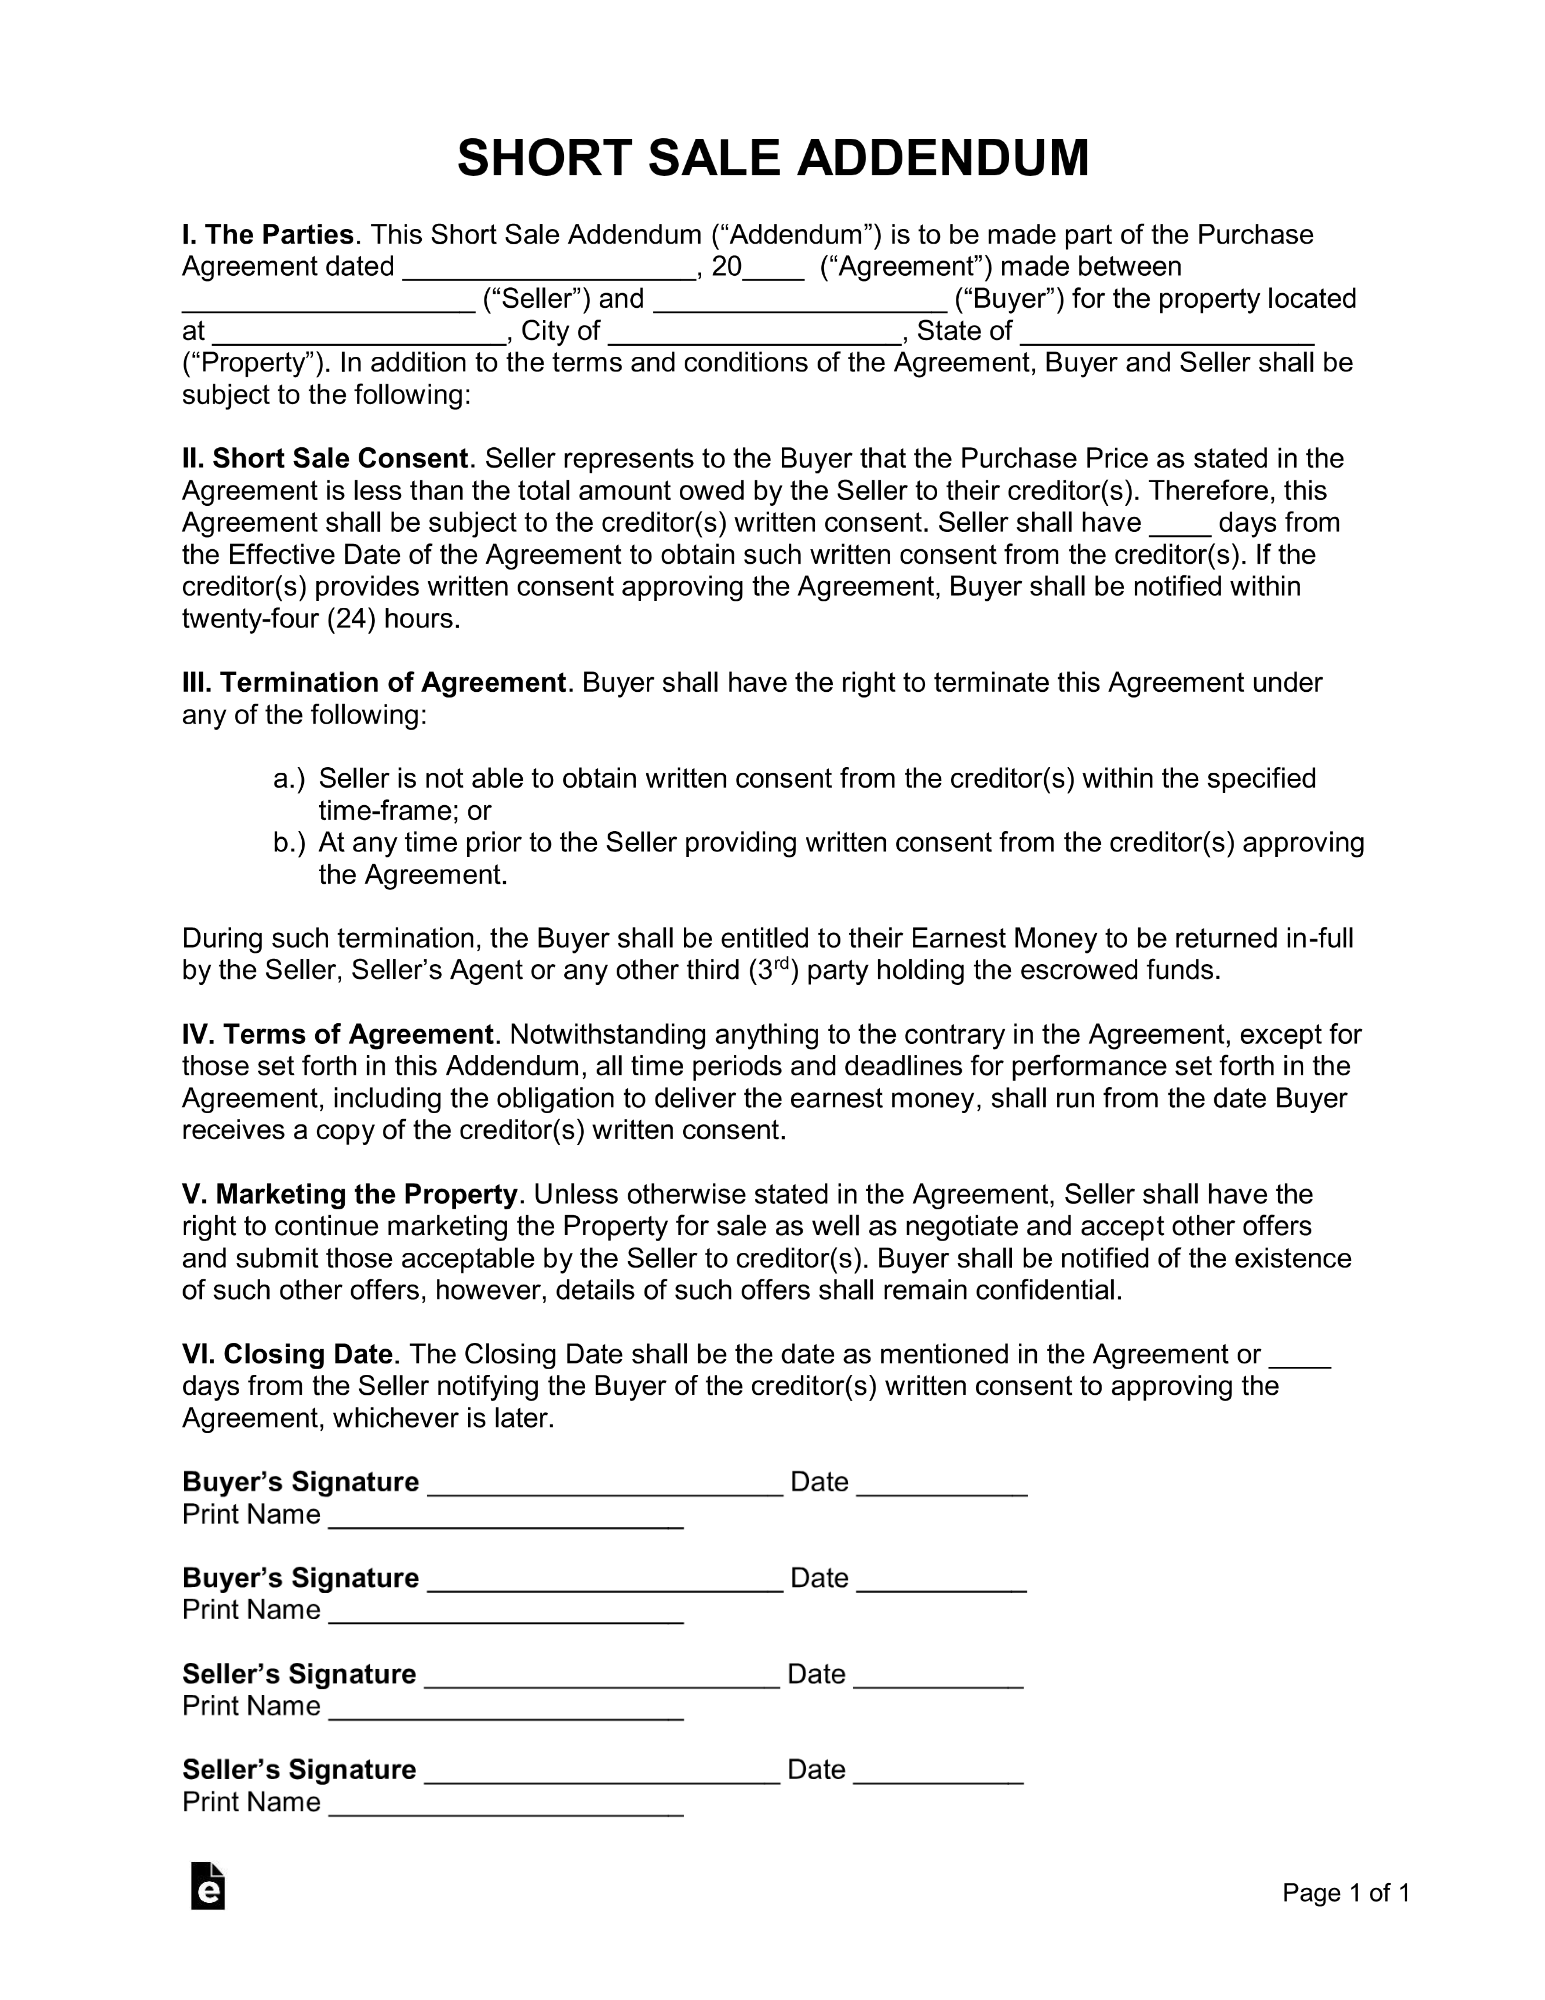
Short-Sale Addendum to Purchase Agreement
Full Conversation


I am a realtor. Representing a seller. Listed home, before settlement found IRS tax lien on the property which exceeded their proceeds. So we asked the current lender to reduce the payoff, which is essentially a short sale process. Their stance is either the IRS payoff is removed from the alta, and it needs to show a minimum lender threshold otherwise the foreclosure process will begin. they want the sales price to go up or reduce all the fees to meet that minimum. The new buyer is accruing delaying costs and the amount to the lender is increasing with the delay. The client said the reason for the IRS lien was due to them not qualifying for a payment plan and they don't have money for attorney to handle this short payoff or IRS situation. We couldn't settle and now we are technically out of contract and standstill. Would it be faster to go to the IRS to resolve or the current lender.

Lexi

Lexi, Chatbot

I understand how challenging this situation must be for you and your client. Have you already attempted to negotiate with the IRS regarding the lien on the property?

The seller did. only got $5K off. If she used a attorney it may have been more, but they told her short sale would be quicker that is why we continued the process except the lender is not budging from their minimum threshold and jeopardizing the deal from going through. If this buyer walks, we would have to go on the market and probably get less which means we would be in the same position.

Lexi

Lexi, Chatbot

What specific terms or conditions has the lender proposed that are causing the current standstill in the transaction?

The lender said to take the lien off the alta, then they will approve it as it will meet the lender's min amount due. Then with short sale approval letter, go to the IRS and have the IRS remove the lien and attach to their social security. The buyer and the new mortgage company will not want to settle with cloud on title and no guarantee the IRS will remove the lien. The lien is 90K in total (which includes penalties and interest)

Lexi

Lexi, Chatbot

Is there anything else the Real Estate Lawyer should know before I connect you? Rest assured they'll be able to help with your IRS tax lien.

No. Want to the know the best direction and questions to ask when I do connect with the attorney who handles situations and what would likely happen if the sellers don't do anything and it goes into foreclosure, what happens with the IRS since they won't have the property that they have a lien on?

Jon

Jon

Hello, and thank you for reaching out! I'm Jon, a licensed attorney with over 14 years of experience, here to help. I understand legal matters can feel overwhelming, but you're in good hands. My goal is to explain things clearly and guide you toward the best possible solution for your situation. Just a quick note: our conversation is for general legal information only and does not create an attorney-client relationship.

Could you let me know which state this property is located in? This will help me understand the legal context better.

Maryland.

Jon

Jon

Thanks for sharing the details. Could you tell me when the IRS lien was first discovered and how long the property has been listed for sale?

I became aware of the lien when we were already under contract. The client didn't disclose to me when signing the listing agreement. Since it was in the alta, the buyer became aware and gave us an extension. March. April 10th was the original closing date and 2nd closing date 5/22.

Jon

Jon

Got it, thanks for the timeline. Have there been any recent communications or negotiations with the lender or IRS since the last closing date attempt?

They already had 1 year forbearance and it was extended for this sale

Jon

Jon

Thanks for that information. Are there any specific deadlines or time constraints from the lender or IRS that you're currently facing?

The last communication with lender was on 5/22. Their response Unfortunately, the current net offer is too low to be considered for a short sale. Please see minimum net listed below. Please have borrower provide the counter no later than 05/27/26 to keep the review open. You will need to upload a contract addendum increasing sales price along with revised settlement. Thank you, Appraisal $620,000.00 VA min net-$521,200.00

IRS is paused as that last amount was the most updated payoff

Jon

Jon

Understood! I believe I have all the information I need. Is there anything else you'd like to add before I start working on your answer? If not, I'll get started right away.

That is all I can think of for now.

Jon

Jon

Got it! I just need a few minutes to put together a complete response for you. It shouldn't take longer than about 4 to 5 minutes, and I want to make sure it's clear and comprehensive. Thanks so much for waiting, I really appreciate your patience.

Jon

Jon

This is a very common type of real estate deadlock where everyone is pushing against different timelines at once. The lender wants a fast answer, the IRS moves slowly, and the buyer is getting frustrated with repeated extensions. The biggest issue is that the lender's suggestion to remove the IRS lien from the ALTA statement is not a real solution and could create even bigger problems.

Even if the lien is removed from the settlement paperwork, the IRS lien still exists in the public records. A federal tax lien attaches to all of the taxpayer's property under (26 U.S.C. § 6321), and a filed notice of lien is effective against later purchasers and lenders under (26 U.S.C. § 6323). A title company in Maryland is not going to issue clean title insurance with a $90,000 federal tax lien attached to the property, and the buyer's lender is unlikely to fund the loan with that lien still in place. The IRS also does not simply transfer a lien onto someone's Social Security number. To clear title legally, the IRS must issue a formal Certificate of Discharge for the property.

The main path forward is usually IRS Form 14135, filed under Internal Revenue Code (26 U.S.C. § 6325(b)(2)(B). Your attorney would argue that after paying the senior mortgage and satisfying the VA minimum net requirement, there is effectively no remaining value in the property for the IRS to collect against. If the IRS agrees its interest in the property has no value, it can approve a discharge of the lien so the sale can close.

The problem is timing. The IRS often says these requests can take at least 45 days to process, which does not fit well with the lender's May 27, 2026 deadline unless an attorney can get the case escalated directly through the local IRS Advisory Office.

Jon

Jon

If the deal falls apart and the property goes into foreclosure, the mortgage lender's lien is usually senior to the IRS lien because it was recorded first. Under standard lien priority rules, a foreclosure by the senior lender can wipe out junior liens, including the IRS tax lien, as long as proper notice is given to the IRS.

That does not erase the seller's tax debt, though. The IRS can still pursue the seller personally for the unpaid balance, interest, and penalties through garnishments, levies, or future liens on other assets. The IRS also keeps a federal right of redemption for up to 120 days after the foreclosure sale, although that right is rarely used unless the property sells far below market value.

Right now, the attorney's main job is to stop the timeline from collapsing. The most important questions are whether they can file an emergency Form 14135 request under IRC § 6325(b)(2)(B), whether they can pressure the lender into granting another extension while the IRS discharge request is pending, and whether commissions or settlement costs can be adjusted enough to satisfy the lender's required minimum net of $521,200.

The attorney should also review the lender's May 22 communication immediately and start working directly with both the lender's loss mitigation department and the IRS Advisory Office before the short sale deadline expires.

What do I do with the current buyer? At this point the buyer wants the property, but not they want to reduce the sales price and increase the seller contribution to 4%, which would reduce the amount left over to around 470K. Current sales price was $635K and their. new lender's VA appraisal was at the sales price. Would it be better to seek another buyer? It is in a desirable county with multiple offers.

Jon

Jon

Reject the current buyer's proposal because reducing the price and adding a 4% seller concession will drop the net proceeds to $470,000, which guarantees the lender will deny the short sale and trigger foreclosure. Your best move is to seek a new buyer from your initial multiple-offer pool who can match the $635,000 price with clean terms, as this easily clears the lender's $521,200 minimum net requirement. Fortunately, the existing VA appraisal sticks to the property for six months, allowing a new VA buyer to bypass the appraisal delay entirely. To keep the file open, immediately notify the short sale negotiator that you are actively swapping out the uncooperative buyer for a backup offer that meets their exact financial threshold. Does that help clear things up for you? If you have any other questions or need more help, please don't hesitate to ask!

The buyer is hanging on. Do I just tell the agent the seller rejects the extension and go from there? If they stay with the current standing where lender is getting $486K, do we give them an extension or just pursue another buyer? What would I disclose when I go back on the market since the short sale is in process but not approved? It needs to meet lender min requirement? and would the attorney try to stop the IRS from adding more penalties and interest?

Jon

Jon

Reject the current buyer immediately and deny the extension, as their $486,000 net offer falls far short of the lender's strict $521,200 minimum requirement and will trigger foreclosure on May 27. When re-listing the property, disclose in the MLS that it is an unapproved short sale requiring third-party approval and a contract that satisfies the lender's specific net threshold. While an attorney cannot stop the daily compounding of IRS penalties and interest on the unpaid tax debt, they can successfully secure a zero-value lien discharge to clear the title for your new buyer. Moving forward with a clean, full-price backup offer is your fastest path to satisfy the lender, protect your client, and successfully close this transaction.

But I do hope the information I provided was helpful and addressed your question. If there's anything else you need, please don't hesitate to reach out, I'm always happy to assist.

Thank you.

Jon

Jon

You're so welcome! I'm thrilled I could help, don't hesitate to reach out if you need anything at all!

Jon

Jon

556 satisfied customers

Jon
Welcome! Have a similar question?

12 lawyers online now

0:00

By messaging AskALawyer, you agree to our Terms and Privacy Policy.

Disclaimer


By messaging AskaLawyer.com, you agree to our Terms and have read our Privacy Policy.

The information provided on AskaLawyer.com is for general informational purposes only and does not constitute legal advice. While we strive to ensure the accuracy and timeliness of the information presented, we make no guarantees regarding its completeness or applicability to your specific circumstances.

Use of this website does not create an attorney-client relationship between you and AskaLawyer.com or any of its attorneys. Communications through this website, including any responses from attorneys, are not privileged or confidential. For advice tailored to your individual situation, we recommend consulting a licensed attorney in your jurisdiction.

AskaLawyer.com disclaims any liability for actions taken or not taken based on the content of this site. We are not responsible for any third-party content that may be accessed through this website. Reliance on any information provided herein is solely at your own risk.

Ask a Lawyer Logo
Ask a Lawyer Logo
Intake Questions
Step  of 3
Loading...

What's your legal question?

Lexi, Chatbot

How would you like your legal question to be answered?

Online

Loading...

How do you like to pay?

By proceeding with payment, you agree to our Terms and Privacy Policy. You authorize us to charge $ today and $ thereafter until canceled. You may cancel anytime in the My Account section to stop future charges.

Total Due:

After purchasing, your chat will begin with an attorney.

By proceeding with payment, you agree to our Terms and Privacy Policy. You authorize us to charge $ today and $ thereafter until canceled. You may cancel anytime in the My Account section to stop future charges.

Total Due:

After purchasing, your chat will begin with an attorney.

After connecting, your chat will begin with an attorney. After choosing, your chat will continue with Legal AI.

It looks like you already have an account with Ask a Lawyer.

We have sent you a magic link to . Click the link in your email to sign in and continue your chat.

spin

Step of 6 •

You'll receive an email at as soon as the lawyer joins the conversation 🙏🏻😊

Over 90% of lawyers connect within 5 minutes. If you're not online at that moment, don't worry — the lawyer will reply to your message while you're away.

You're also welcome to stay in the chat while waiting to be connected 💬✨

Waiting for lawyer

We couldn't send your message. Please try again.

Your lawyer will reply as soon as possible

If there’s a delay, please don’t worry. Your chat will stay open, and they’ll get back to you as soon as they can. There’s no rush on your end either. You’ll receive an email notification as soon as there’s a new message.

You've reached your AI chat limit

Upgrade your plan to continue chatting and get instant domain-specific answers.

0:00